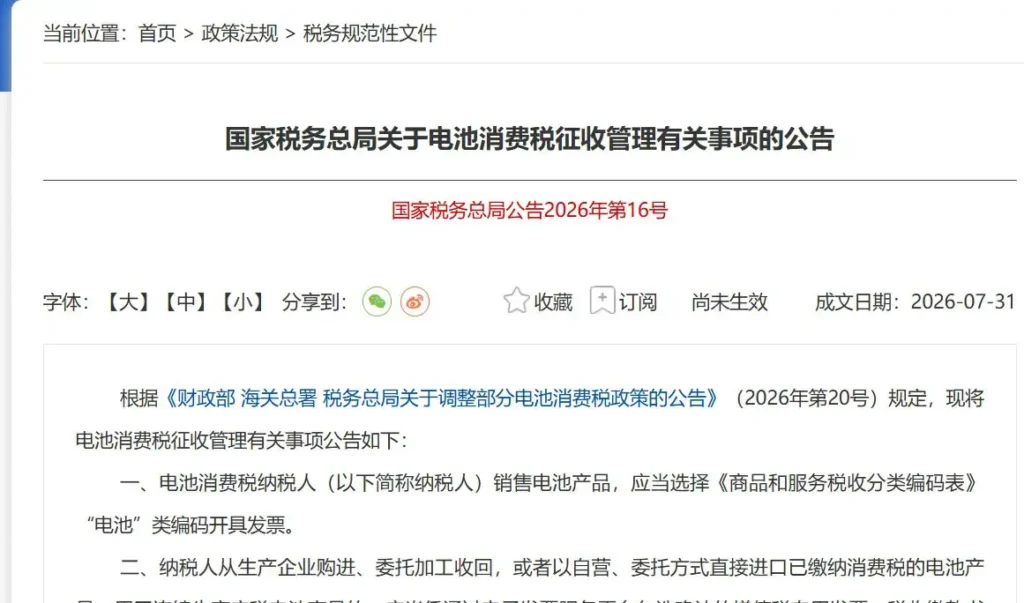
State Taxation Administration Announcement No. 16 of 2026 took effect on 1 September 2026. It requires battery sales invoices to use the relevant battery tax-classification codes. Where tax-paid batteries are used in the continuing manufacture of taxable batteries, qualifying documentation supports calculation of the available tax credit, with a dedicated credit ledger required. Products receiving tax reductions or exemptions require testing reports against the applicable national standards and corresponding product lists. This announcement governs administration and documentation; the separate 2026 Announcement No. 20 sets the relevant tax-policy changes.